
What to Ask Your Mortgage Broker
The questions to ask a mortgage broker fall into three groups: who the broker is and how they get paid, why they are recommending this particular loan, and what happens between the application and the day you collect the keys. Bring all three lists to your first meeting. A broker who does the job properly will be glad you did.
I say that as a broker. Since 1 January 2021, mortgage brokers in Australia have been bound by a best interests duty under the National Consumer Credit Protection Act. The loan I recommend has to be the one that suits you, not the one that is easiest to process or pays more. Bank staff selling their own bank's products are not held to that standard. Borrowers have noticed: MFAA data shows brokers arranged 81.6 per cent of all new residential home loans in the June 2026 quarter, a record. With that many people relying on a broker, it pays to know how to test one.
Why interview your broker at all?
Because the first meeting is usually free and the loan is not. Most brokers, including us, charge nothing for the initial appointment, so the only cost of asking hard questions is 20 minutes. The loan on the other side of that conversation may be the largest debt you ever carry, and small differences in structure show up as thousands of dollars over the term. The questions also show you whether the broker is listening. If every answer circles back to a sales line, you have learned something.
Questions about the broker
1. Are you licensed, and what is your credit representative number?
Every broker in Australia must hold an Australian Credit Licence or be an authorised credit representative of a licensee. Ask for the number and check it on ASIC's professional registers before you hand over a payslip. Mine is Credit Representative 541982, and it sits in our website footer, where it should be.
2. How many lenders are on your panel, and how many do you actually use?
The two numbers are different, and the second one matters more. A panel of 30+ lenders means little if 90 per cent of the broker's loans go to two banks. At Synergy, we compare across a panel of more than 20 banks, regional lenders and non-bank lenders. Ask which lenders the broker has settled loans with in the past year and why. The answer should be about client fit, not convenience.
3. How are you paid?
In most cases, the lender pays the broker, not you. There is an upfront commission when the loan settles, then a smaller trail commission each year the loan stays in place. If you refinance or pay the loan out early, usually within the first two years, the lender can claw the upfront commission back. All of this must be disclosed in a Credit Guide before you proceed, so ask for it. Some brokers also charge a fee for complex or small loans. Ours is generally no cost to you, and where a fee applies, we tell you before anything is signed.
4. Are you a member of the MFAA or FBAA, and where do I go if something goes wrong?
Membership of the Mortgage and Finance Association of Australia or the Finance Brokers Association of Australia commits a broker to a code of practice and ongoing education. Separately, every licensee must belong to the Australian Financial Complaints Authority, the free external dispute service if a complaint cannot be settled with the broker directly. Ask how internal complaints are handled and how long they take.
Questions about your loan
5. Why this lender, and why this product?
The broker should name at least two other options they weighed and explain why those lost. Under the best interests duty, that reasoning is meant to be documented anyway. If the only explanation is the rate, push harder. Lender policy on your income type and the property you are buying matter as much.
6. What is the comparison rate, and what fees sit behind the headline rate?
The headline rate is what gets advertised. The comparison rate folds in most fees and charges over the life of the loan, and lenders must show it by law. It is calculated on a $150,000 loan over 25 years, so it is a blunt tool on a $700,000 mortgage, but a wide gap between the two tells you fees are doing work somewhere. Ask for application, package, valuation and discharge fees as separate line items.
7. Do I need an offset account, redraw, or both?
An offset is a transaction account linked to your loan; the balance reduces the interest you pay while staying available to spend. Redraw lets you take back extra repayments. Offset usually carries a package fee, so it only pays for itself if you keep a meaningful balance in it. If you might rent the home out later, the choice has tax consequences, and that is where I send clients to their accountant.
8. Should I fix, stay variable, or split?
No broker can tell you where rates are heading, and a good one says so. What we can explain is what a fixed rate costs in flexibility: caps on extra repayments, break costs if you sell or refinance early, and often no offset. Ask what happens when the fixed term ends. The revert rate is where lenders make their money back.
9. Will I pay lenders mortgage insurance, and how could I avoid it?
Lenders mortgage insurance generally applies when you borrow more than 80 per cent of the property value. It protects the lender, not you, and it can run to tens of thousands of dollars on a Sunshine Coast purchase. Ask whether a guarantor, the federal Home Guarantee Scheme, an LMI waiver for certain professions, or a slightly smaller loan would get you under the line.
10. How did you work out my borrowing capacity?
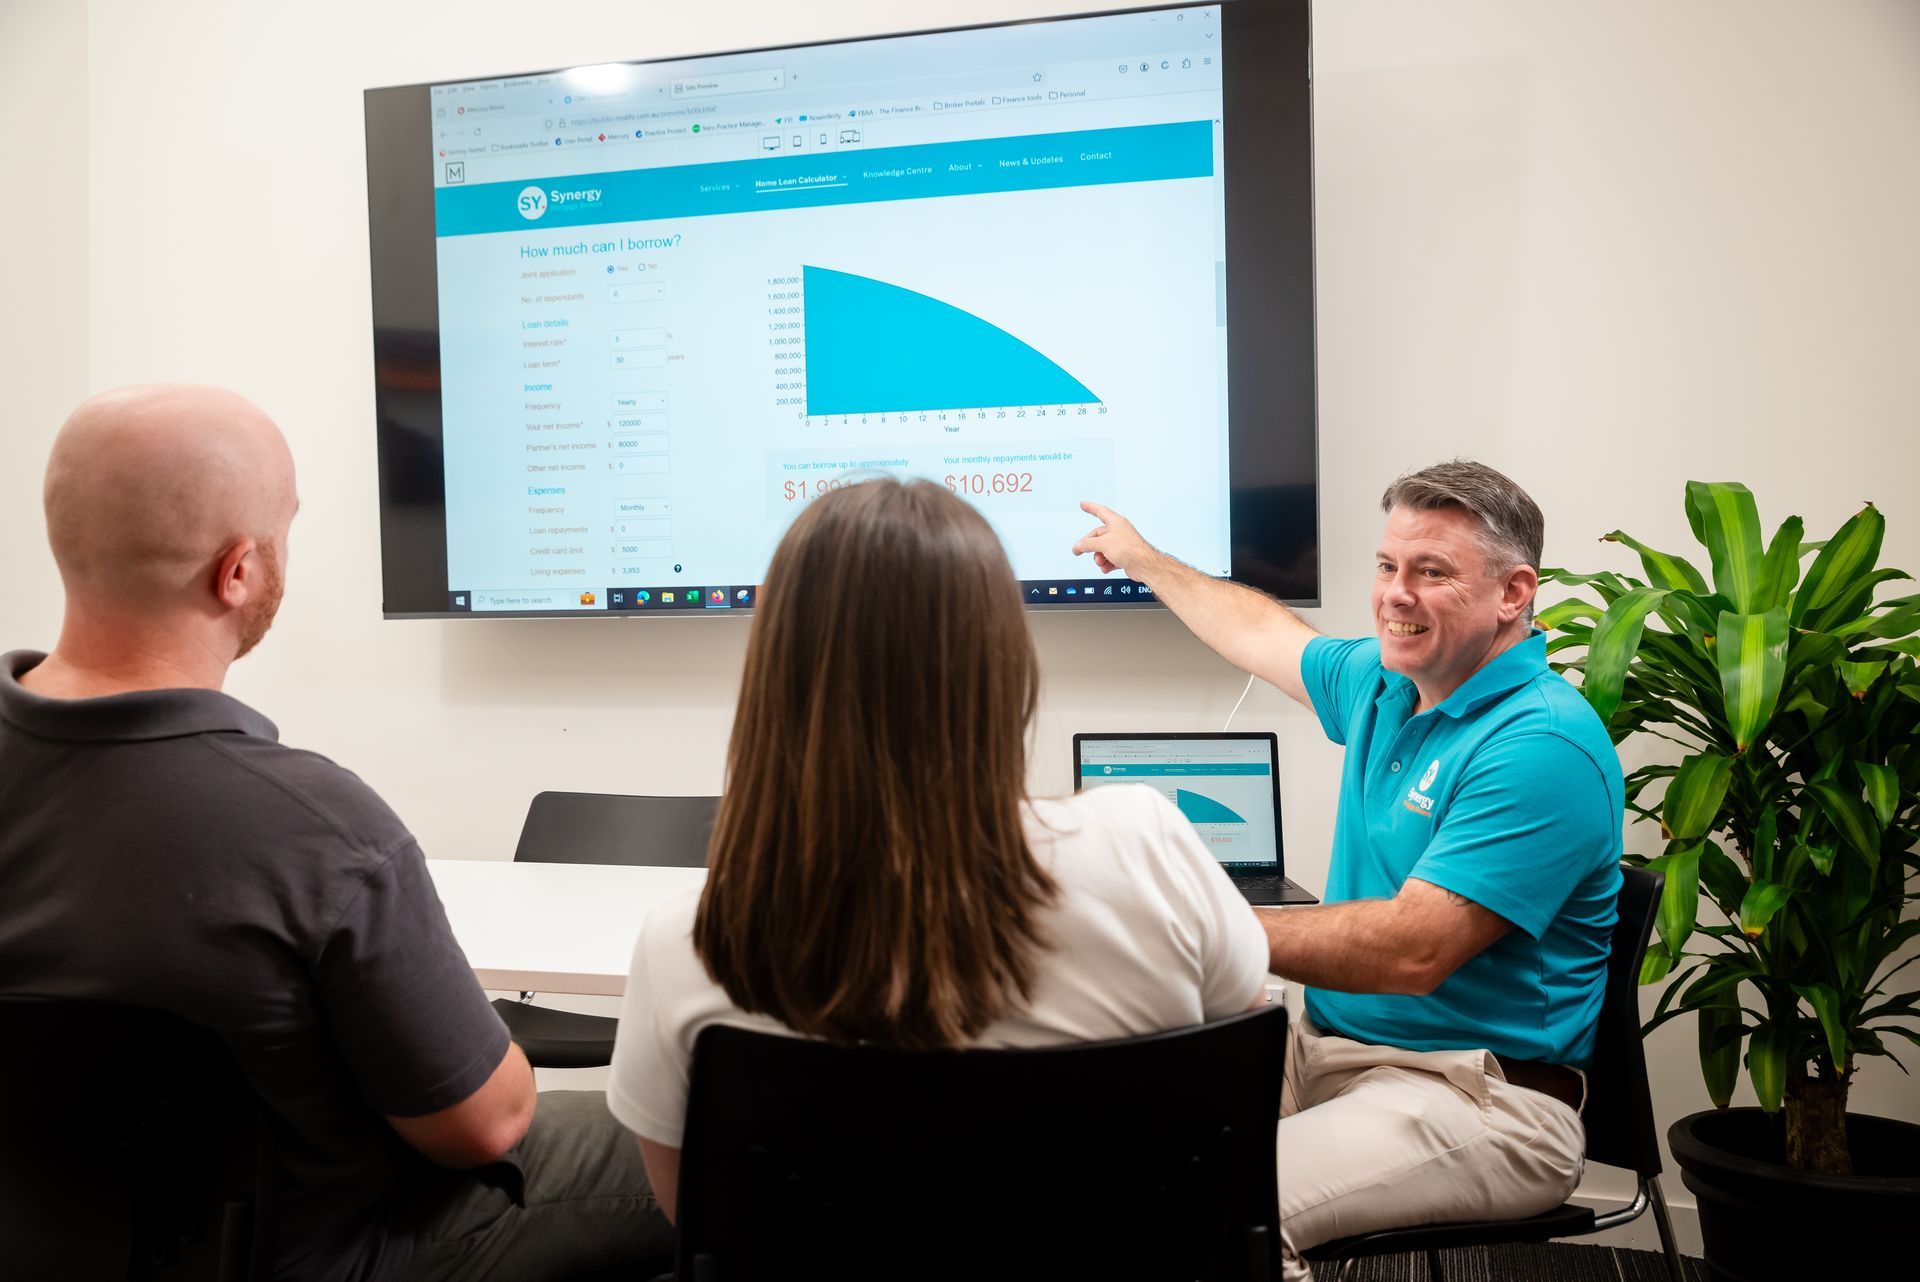
Lenders do not assess you at the rate you will actually pay. APRA requires them to test repayments at the loan rate plus a buffer of at least 3 percentage points, a setting it reconfirmed on 28 May 2026. They also apply living expense floors, shade rental and bonus income, and count credit card limits rather than balances. Ask which assumptions produced your figure. Closing an unused card can shift it.
11. How long is my pre-approval valid, and what could void it?
Most pre-approvals last about 90 days, some up to six months. A new job, a car loan, a rate rise or a valuation under the contract price can unwind one. Ask whether the lender's credit team fully assessed it or whether it is a system-generated indication, because they are not the same thing.
Questions about the process
12. How long will this take, who talks to the lender, and what happens after settlement?
Three questions in one, because they belong together. Turnaround varies by lender; some approve a clean application within days, others take a fortnight or more when volumes are high. Your broker should quote the current turnaround for the lender they are recommending, and they should be the one chasing the lender, answering assessor queries and coordinating with your conveyancer so settlement lands on the contract date.
Then the part most borrowers forget. What happens in 12 or 24 months? Trail commission is meant to pay for ongoing service, so ask whether the broker reviews your rate against the market, contacts you before a fixed term ends, and helps with a refinancing page if your lender has drifted. At Synergy, the answer to all three is yes. Hold us to it.
What a good answer sounds like
Specific, documented and a little boring. A good broker hands you a Credit Guide without being asked twice, names the lenders they compared, shows the comparison rate beside the headline rate and explains the buffer behind your borrowing figure. They will not promise approval before they have seen your documents, and they will not quote a rate before they know which lender you are going to.
If the answers stay vague, or you feel steered towards one product, keep looking. And if you are a first home buyer on the Sunshine Coast or in Toowoomba, our first home buyers page covers deposits, grants and the schemes currently open.
Frequently Asked Questions
What should I bring to my first meeting with a mortgage broker?
Your last two payslips, your most recent tax return or notice of assessment if you are self-employed, three months of bank statements, statements for any existing loans or credit cards, and photo ID. If you have a property in mind, bring the listing or contract. Our Maroochydore and Toowoomba offices are open Monday to Friday, 8 am to 5 pm, and we also meet by phone or video.
Do I have to pay a mortgage broker in Australia?
In most cases, no. The lender pays the broker an upfront commission when the loan settles and a trail commission while it stays in place. Some brokers charge a fee for complex or small loans, and they must disclose it before you proceed. At Synergy, our service is generally at no cost to you, and if a fee applies in your situation, we tell you before any application goes in.
What should a first home buyer ask a mortgage broker?
Start with three: how much deposit do I really need, which government schemes am I eligible for, and will I pay lenders mortgage insurance? In Queensland, that means asking about the First Home Owner Grant for new builds, transfer duty concessions and the federal Home Guarantee Scheme. Then ask what everyone should: how the broker is paid, which lenders they compared and why this one won.
If you would like to put these questions to a broker who welcomes them, contact us on
1300 324 588 or visit
Synergy Mortgage Brokers in
Maroochydore or
Toowoomba City
About the Author
Brendan Philp, Director, Synergy Mortgage Brokers
Brendan Philp is the Director of Synergy Mortgage Brokers, a Sunshine Coast and Toowoomba-based brokerage. He holds a Bachelor of Commerce (Business Law) and a Diploma of Finance and Mortgage Broking Management, and works with first home buyers, upgraders, investors and self-employed borrowers across South East Queensland. Credit Representative 541982. This article reflects general market commentary and is not financial advice.
Subscribe Today!
Stay in the loop - subscribe to our newsletter for the latest trends and insights.
Contact Us Today
We’d love to hear from you. Choose the most convenient method and we’ll get back to you as soon as we can.
Contact Us